
Photo Credit: blogs.timesofisrael
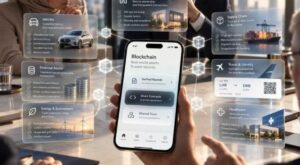
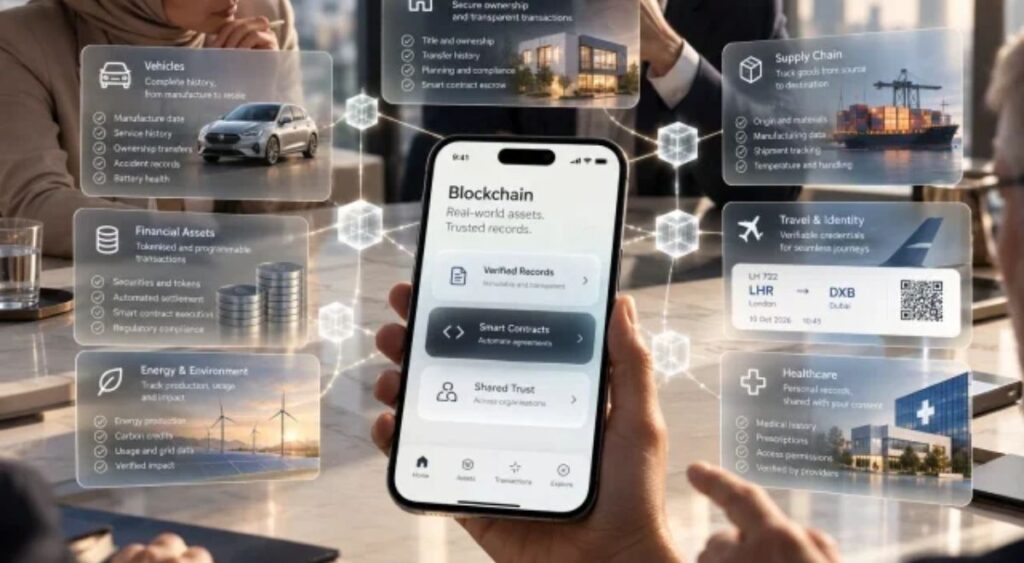
Blockchain technology is widely associated with Bitcoin and cryptocurrencies, but its potential extends far beyond financial markets. From vehicle ownership and supply chain transparency to digital contracts and product verification, the technology could change how businesses establish trust, protect information and demonstrate accountability.
As cryptocurrencies continue to attract attention from investors, regulators and financial institutions, the technology behind them is developing applications across other industries. Blockchain offers a way for multiple parties to maintain a shared digital record without placing complete control in the hands of a single organisation.
Its significance lies not in guaranteeing that information is true, but in making records easier to verify and harder to change without detection.
What Is Blockchain and How Does It Work?
Consider someone purchasing a used vehicle. The seller claims the car has travelled 40,000 miles, has never been involved in an accident and has undergone regular maintenance.
Confirming those claims could involve checking service records, contacting dealerships, reviewing insurance information and arranging an independent inspection. Even then, important details may be missing because different organisations maintain separate records.
Blockchain offers a potential solution by allowing authorised participants to contribute information to a shared digital history.
Unlike a conventional database managed by a central administrator, a blockchain organises records into groups known as blocks. Each block is connected to the previous one using cryptographic technology, creating a chronological chain of information.
For a vehicle, this could include its manufacturing date, first ownership registration, maintenance at 10,000 miles and battery replacement at 35,000 miles.
Once information is recorded and confirmed, changing an earlier entry without detection becomes considerably more difficult. Copies of the ledger may also be distributed among participating computers, reducing dependence on a single record keeper.
The US National Institute of Standards and Technology (NIST) describes blockchain as a distributed digital ledger designed to make changes detectable and resist unauthorised alterations.
However, blockchain does not automatically verify whether information entered into the system is accurate. Its main advantage is protecting the integrity of records after they have been accepted. <Cite ref=”turn879655search5″/>
The Role of Cryptographic Hashing in Blockchain Security
One of blockchain’s essential security features is cryptographic hashing, a mathematical process that converts digital information into a fixed-length fingerprint.
The concept is similar to the checksum used to verify downloaded files. When a file changes, its calculated fingerprint will generally change as well, indicating that the original information has been altered.
Blockchain applies this principle to connect individual blocks. Each new block includes a cryptographic reference to the previous block, creating a series of interconnected records.
If someone attempts to modify an earlier transaction, the modification changes its cryptographic fingerprint and disrupts the connections with subsequent blocks.
Other network participants can detect these inconsistencies when validating the blockchain.
Yet cryptography alone cannot determine which transactions should be accepted. Blockchain networks also require consensus mechanisms that establish agreement over the legitimate transaction history.
Bitcoin relies on proof of work, where miners compete through computational processes to validate and add new blocks. Other networks use proof of stake, which generally requires validators to commit cryptocurrency as collateral and face potential penalties for misconduct.
Although their approaches differ, both systems aim to establish an agreed transaction history without relying entirely on a central authority.
The result is a digital record designed to be verifiable and resistant to manipulation rather than an automatic guarantee of truth.
Smart Contracts: Automating Agreements Through Blockchain
Blockchain can also support smart contracts, computer programs that execute predetermined instructions when specified conditions are met.
In conventional business transactions, banks, legal representatives and other intermediaries frequently help verify agreements, process payments and confirm whether contractual obligations have been fulfilled.
Smart contracts can automate parts of these processes.
For example, a company might agree to pay a supplier £50,000 after receiving and verifying a shipment. A smart contract could automatically release the payment once an authorised system confirms delivery.
Such arrangements may reduce paperwork, accelerate transactions and limit certain administrative costs.
However, smart contracts have important limitations.
A program cannot independently determine whether a shipment arrived in satisfactory condition. It must obtain reliable information from external sources, often through services known as oracles.
If an external system provides incorrect information, a smart contract could execute its instructions correctly while producing an unintended financial outcome.
Smart contracts are also not necessarily legally enforceable agreements simply because they operate on a blockchain.
Their effectiveness depends on the reliability of their programming, the information they receive and the legal arrangements governing the transaction.
Digital Vehicle Records Could Transform the Used-Car Market
Vehicle history provides a practical example of how blockchain could improve transparency between businesses and consumers.
Under a blockchain-supported system, each vehicle could have a persistent digital identity connected to its Vehicle Identification Number (VIN).
Manufacturers, authorised dealerships, insurers and inspection centres could record relevant events throughout the vehicle’s life.
These might include ownership transfers, accident repairs, servicing, component replacements, insurance claims and manufacturer recalls.
Rather than relying on documents held by separate organisations, an authorised buyer could access a consolidated record showing the vehicle’s previous maintenance and ownership history.
Digital signatures would help identify which organisation submitted particular information, while cryptographic verification could reveal subsequent unauthorised changes.
Sensitive personal or commercial information could remain in protected databases outside the blockchain, with only verification fingerprints stored on the ledger.
The concept has already attracted automotive industry interest. In 2017, Renault announced a blockchain-based digital car maintenance book prototype developed in collaboration with Microsoft and VISEO.
Related developments are also taking place in European regulation.
Under the European Union’s Batteries Regulation, digital battery passports are scheduled to become mandatory from 18 February 2027 for electric-vehicle batteries, light means of transport batteries and industrial batteries exceeding 2 kWh.
These electronic records are intended to provide specified information about batteries, supporting transparency throughout their life cycles. <Cite refs={[“turn879655search3″,”turn879655search0”]}/>
Importantly, the regulation does not require blockchain specifically. Digital product passports can operate through other technological systems.
This highlights a crucial distinction: businesses need reliable information, and blockchain is only one possible way to manage it.
Where a single trusted organisation already controls the entire record system, a conventional database may remain the more practical and economical option.
Blockchain becomes more relevant when independent organisations need to maintain a shared history without giving one participant unrestricted authority.
Blockchain in Supply Chains: Improving Traceability and Accountability
Global supply chains involve complex relationships between manufacturers, suppliers, transport operators, distributors and retailers.
A pharmaceutical product, for example, may contain ingredients sourced from different countries, undergo manufacturing elsewhere and travel through several distributors before reaching a hospital.
At each stage, companies must verify product authenticity, storage conditions, documentation and regulatory compliance.
Blockchain could help establish a shared record of these activities, allowing authorised participants to verify where a product has travelled and which organisations handled it.
For temperature-sensitive medicines, recorded transport data could help determine whether appropriate storage conditions were maintained.
Similar applications are being explored for food products, electronics, aircraft components, precious metals and critical minerals.
A diamond could carry a documented history of its origin and ownership. An aircraft component could have a traceable maintenance record, while an electric-vehicle battery could have information about its materials, repairs and eventual recycling.
Such systems could improve product recalls, reduce administrative reconciliation and help regulators investigate problems.
However, the technology cannot independently establish whether a supplier’s claims are genuine.
If a company falsely records that a product was ethically sourced, blockchain may preserve that inaccurate declaration.
Meaningful accountability therefore requires physical inspections, reliable sensors, independent verification, digital signatures and appropriate regulatory oversight.
Blockchain can protect the history of a claim, but establishing the truth behind it remains a human and institutional responsibility.
Why Bitcoin Challenged Traditional Money Systems
Although blockchain has applications across multiple industries, its global recognition began with Bitcoin.
Introduced in a 2008 white paper by the pseudonymous Satoshi Nakamoto, Bitcoin proposed a peer-to-peer electronic cash system that could operate without a traditional financial intermediary maintaining the central transaction ledger.
Its emergence coincided with the global financial crisis, when confidence in banks and financial institutions had been seriously undermined.
Bitcoin introduced the possibility of transferring digital value through a network governed by publicly verifiable rules rather than a single financial institution.
Another defining characteristic was its predetermined supply.
Traditional fiat currencies, including the US dollar and British pound, are not backed by fixed quantities of gold. Their purchasing power depends on economic conditions, monetary policy, institutional credibility and public confidence.
Central banks influence monetary conditions, while commercial banks also create deposit money through lending.
Although these activities operate within regulatory and economic constraints, excessive monetary expansion can contribute to inflation and currency instability.
Bitcoin offered a different monetary model.
Its protocol is designed to limit the eventual supply to approximately 21 million bitcoins, with new coins issued through mining rewards.
These rewards decrease approximately every four years through events called halvings, progressively reducing the rate at which new bitcoins enter circulation.
This predetermined issuance structure helped establish Bitcoin’s reputation as a form of digital gold.
However, a limited supply does not automatically make an asset a stable store of value. Demand, market confidence, adoption and regulatory developments continue to influence Bitcoin’s price.
Bitcoin and Digital Gold: Understanding Artificial Scarcity
Bitcoin’s comparison with gold reflects the different ways both assets establish scarcity.
Physical gold is difficult to obtain because mining requires geological exploration, specialised equipment, labour, energy and substantial investment.
Bitcoin creates scarcity through mathematical rules and computational competition.
Under its proof-of-work system, miners use computing equipment to search for solutions that satisfy the network’s difficulty requirements.
The network periodically adjusts those requirements to maintain an average interval of approximately ten minutes between blocks.
When more computing power joins the network, the difficulty can increase rather than allowing the overall supply of newly issued bitcoins to grow faster than scheduled.
Both gold mining and Bitcoin mining therefore involve resource expenditure, although their underlying characteristics differ significantly.
Gold is a physical commodity with industrial applications and a long history of monetary use. Bitcoin exists digitally, and its usefulness depends on the security, acceptance and continued operation of its network.
The electricity and computing resources used in Bitcoin mining also do not determine its market value.
Similarly, its supply limit is maintained through software rules accepted by network participants. Although changing those rules would be difficult and controversial, the limit is not a physical law.
Bitcoin’s scarcity can be an important factor in investor demand, but it cannot eliminate market volatility or guarantee future purchasing power.
Its long-term value depends on whether people and institutions continue to regard it as useful, secure and worth holding.
Beyond Cryptocurrency: Blockchain’s Wider Economic Potential
While Bitcoin introduced blockchain to a global audience, digital currencies represent only one part of the technology’s possible future.
Its broader appeal lies in helping organisations maintain records that multiple parties can inspect and verify without depending entirely on one administrator.
For businesses, this could mean better oversight of supplier relationships, more reliable product histories, faster verification of documents and improved coordination between independent organisations.
For consumers, it could mean greater visibility into the ownership, maintenance and origins of products they purchase.
Governments and regulators could also benefit from systems that make authorised records easier to audit and changes more difficult to conceal.
However, blockchain is not necessarily the right solution for every information-management problem.
Its implementation can introduce additional costs, technical complexity, privacy concerns and governance challenges. Many organisations may achieve similar objectives more efficiently using established databases with strong access controls and independent auditing.
The decisive question is not whether a system uses blockchain, but whether it solves a genuine problem involving trust, verification or accountability.
As industries place greater importance on transparent records and verifiable digital identities, blockchain may find its most lasting applications far beyond cryptocurrency trading.
Bitcoin demonstrated that digital transactions could be recorded without a conventional central ledger administrator. The larger opportunity may be applying that principle wherever independent organisations need to share information, establish responsibility and maintain confidence in records.
Ultimately, blockchain’s most important contribution may not be creating a new form of money, but changing how trust is established in an increasingly digital economy.